
Editorial
A bank counter pitch for retail government bonds; why the reader put the money aside until its purpose was clear
Contents
The situation
At a bank counter, I was told, “Government bonds for individuals are issued by the state, so they are safe.” They said the interest rate was higher than a deposit, and I almost applied on the spot.
What stands out
- These bonds can be bought from 10,000 yen. The maturity and the way the rate is set differ by type (a 10-year floating-rate type, and 5-year and 3-year fixed-rate types).
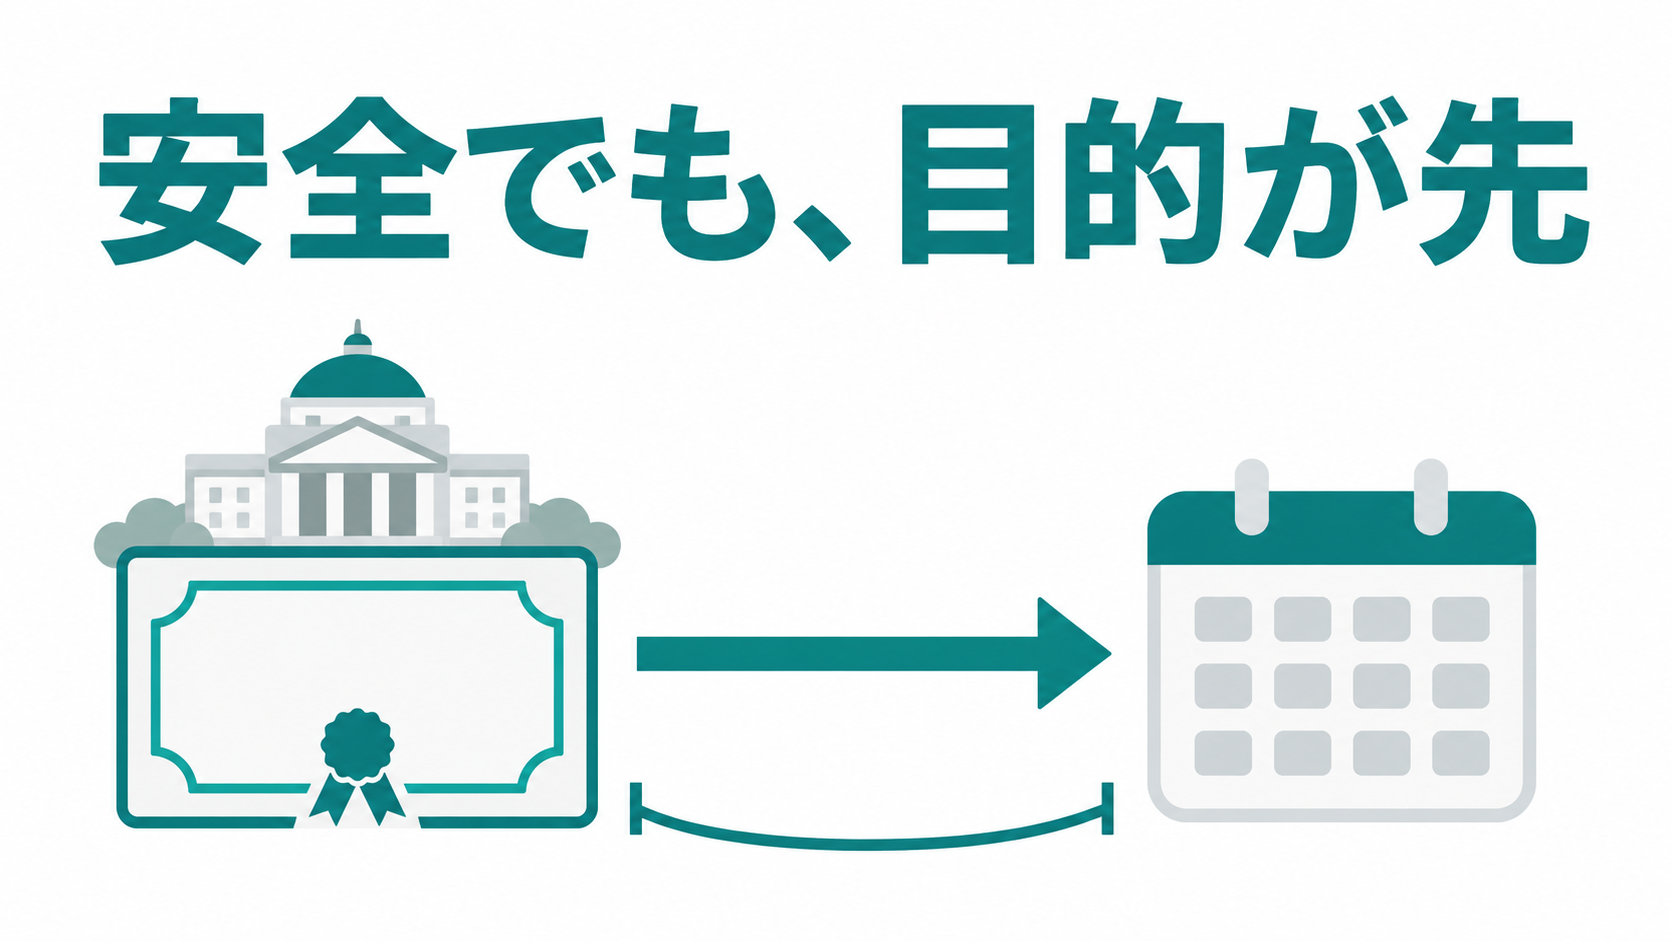
- The principal is repaid at face value, but this does not mean you can withdraw whenever you like. In principle, you cannot sell (cash in early) for one year after buying. If you cash in early after that, an amount equal to interest for a set period is deducted.
- When prices rise, even if the principal does not shrink, what the money can buy may shrink.
- The terms (such as the rate) change with each issue. You need to check the latest details in the Ministry of Finance guide to government bonds for individuals.
Why one might pass
When I was offered it, I had not decided what the money was for (was there a plan to use it soon, or was it a reserve for living costs). I did not want to lock the money away for a year without a purpose, so I paused for the time being.
What could change the decision
If I could set aside a reserve for living costs separately, and expected not to use this money for more than a year, I could compare it again as one option among others. This is not a suggestion to buy. Even then, I would check the rate and conditions in the latest guide. There is no need to judge this decision by how rates move afterwards.
What this case shows
- “Safe” is about the payment of principal. Ease of withdrawal and the effect of prices are separate questions.
- Decide first what the money is for and until when you will not need it.
- The terms change with each issue, so read the latest guide before buying.
Related: Why record the deals you passed on: a checklist for skipping decisions
We also welcome your own story of an investment you passed on. Send your story.
This article is a story rebuilt from examples shared by readers, with details changed so that no individual can be identified. Some numbers and conditions are illustrations. It is not a recommendation of any product or investment. Terms can change, so check the latest guide from the Ministry of Finance or the seller before applying.
Found this useful? Let us know (anonymous).
Read next
Passing on gold in a hurry after hearing it hit a record high
Gold in the news at a record high; why the reader could not explain the reason to own it and passed
Related articles
Passing on the No. 1 themed fund in the popularity ranking
A themed investment fund ranked first and up sharply; why the reader could not explain its contents and costs and passed
Passing on a crypto asset promoted as “sure to go up”
A coin promoted on social media as "sure to rise 10 times"; why the reader could not explain it and passed
Passing on a small stock that surged on social media buzz
A small stock surges in days on social media buzz. A story about passing when buzz is the only reason and nothing can be checked.
Passing on a hot IPO on its first trading day
On the first trading day, buying pours in and the price runs far above the offer price. A story about not chasing a first-day price set by supply and demand.